Monday, December 1, 2014

Dash giving free $5 for you to spend just for signing up their app!


Get $5 cash now, just by signing on to DASH app.


http://www.dash.com.sg/dash-for-cash.html?uniqueKey=SU5KGRDVJA391X8E

You can just click on the above link, sign up and you can get $5 cash to spend anyway you like it.
In case you have not heard of Dash, it is an app designed by Standard Chartered Bank and Singtel to have an e-Wallet in your phone. Had dinner with friends and want to split the bill? Use Dash. Want to buy a koi bubble tea? Use dash. Transfer a few dollars to a friend immediately? Just use Dash...

Beside this free $5, they are having a series of promotions for Dash.

Big fans of Bubble tea? Every 3 Koi will get u $1 cashback.

Watson shopping? Beside the discounts and sales in watson, there is an additional 10% discount on all watson purchases if you use the Dash app to pay.
This is the good deal that I had been waiting for... there are many daily products that I love to get from watson coz its so much cheaper than in other shops....

Happy Shopping!


Sunday, November 23, 2014

Amazing trading blogs to read now

First of all, the regular blog that I blog a lot more frequently.

www.wiseoftheday.blogspot.com
Full of non-trading stuff, funny and nonsense articles...
Its a blog I started to share interesting stuff that will make us laugh and ponder...
The updates are much more frequent there!


These are the blogs that I read regularly.

For Options Trading
http://wilddreamsinoptionsselling.blogspot.sg/
By wild-dreams

He has a successful record in trading options on S&P  futures (mini ES).
Recently he started venturing into commodities options, such as crude oil, soyabeans etc.
Good to know his entry points.


http://theoptionsjourney.blogspot.sg/
By Tony.

He deal with options in Nikkei N225 and KOSPI K200.
The good thing about this blog is that whenever his trade goes wrong, you can see how he attempt to repair and salvage the trades to reduce his losses. All traders will hit some losses, instead of plain Stop - Loss, it is good to repair the trade, sometimes in advance.


Cillin Trading Journal
http://cillinsg.blogspot.sg/

Journal of a trader who trades from US Dollar Index, to commodities, to equity indices to forex.
He has many charts and analysis. My favourites are his COT (Commitments of Traders)
COT is a good guide to understand if you are dealing with futures in your trade. Find out how the big boys and the commercials are handling the commodities supply and demand swings.

The Weekly COT Report

The weekly report details trader positions in most of the futures contract markets in the United States. Data for the report is required by the CFTC from traders in markets that have 20 or more traders holding positions large enough to meet the reporting level established by the CFTC for each of those markets.1 These data are gathered from schedules electronically submitted each week to the CFTC by market participants listing their position in any market for which they meet the reporting criteria.
The report provides a breakdown of aggregate positions held by three different types of traders: “commercial traders,” “non-commercial traders” and “nonreportable.” “Commercial traders” are sometimes called “hedgers”, “non-commercial traders” are sometimes known as “large speculators,” and the “nonreportable” group is sometimes called “small speculators.”

For stocks analysis blogs, I recommend these 2 for American stocks.
I also love Seeking Alpha for its stock recommendation and outlooks.
For example this article on Dividend growth investing
http://seekingalpha.com/article/2704595-dividend-growth-investing-total-return-and-indexing-revisited

http://www.stockta.com/
And StocksTA for TA analyst on stocks. I use if I have to buy USA stocks to sell covered calls. (astonishing I kept getting assigned on calls, and I had to sell covered puts)


And for those who loves Singapore IPOs,
http://www.singapore-ipos.blogspot.sg/
This guy is awesome, he will provide a wonderful write up on any IPO that is getting listed in Singapore, and give a thoughtful analysis and the statistics for the IPO.
Whenever there is a new IPO coming, I will rush to his website for the latest read.


For all trading, I highly recommend using Interactive Brokers.

Monday, November 17, 2014

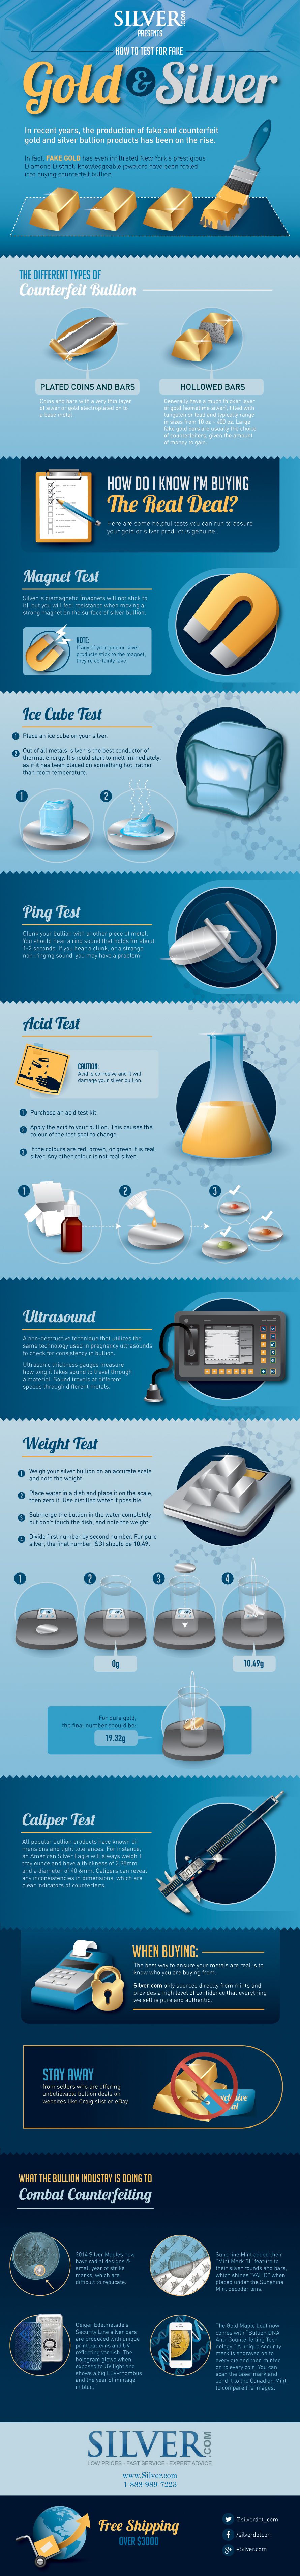
How to test for Fake Silver? How to test for Fake gold?


I took this graphic from www.silver.com
Pretty informative.
Great to know how to test for real silver, or how to test for real gold.
Happy Buying!

Monday, November 3, 2014

Book Summary- Trading Options at Expiration

Trading Options at Expiration: Strategies and Models for Winning the Endgame 

Jeff Augent


Core Points:-
Short straddles later on expiration day, when pinning is evident (such as it moved to 1 new strike and back to the old strike)
Long straddles during midday IV stability window (after 1030am)
Ratio trades are best to hedge against both sides 1:3, long/short OTM calls
Can also do evening before expiration days.

Reasons to trade on Expiration Day- Chapter 1

Expiration trading is a mathematical game distinctly different from stock trading
- reduced risk/return profile
- limited market exposure
- extremely high returns on a percentage basis
- directional neutral strategy

1) Implied Volatility Collapse- IV drop a lot on expiration, price distortions as large as 30% on Thurs and 100% on expiration Friday for ATM options

Friday Market opens- IV is stable or rising from open till 11:00. Volatility drops from 30% to 20%, where it is stable till 14:00. Then a sharp steady decline in IV till close.
Long positions designed to profit from underlying price changes are best structured after IV stabilises early in the day
Conversely , traders who structure early short positions often find that midday price changes can be costly, especially if IV temporarily rises.
Simple short positions designed to benefit from IV collapse perform best late in the day, after stock stabilises near a strike price and most large positions have been unwound. 

IV collapse can become more dramatic when unusual events distort the profile (earnings, etc)

GOOG - $538
Long $530 calls, and short $540 calls ratio 1:3


2) Strike Prices Effect- Stock prices hover around strike prices (pinning effect), can gauge using Open interest, and distance to nearby strikes.
pinning behavior due to delta hedging large numbers of long positions.

OR it jump crosses many strike prices and pin at later strike prices
stock prices hover around strike prices as large institutional investors unwind complex positions ahead of expiration.

Stocks such as AAPL and MA that often fail to close near a strike price, but have a very high strike cross frequencies are excellent candidates for certain types of expiration day trades such as long straddles. (pg 38)
Pinning - (page 41) rarely mentioned result of pinning is tendency of some stocks to exhibit unusually large price changes on Monday following expiration.
Tendency can be exploited by purchasing long straddles just a few minutes before expiration on stocks that close expiration Friday pinned to a strike price.
Statistically speaking, these straddles generate disproportionately large returns because they are mispriced.

3) Time Decay- time decay significantly on Thurs before Expiration Friday (31.3% remaining time), and the Friday 1 week before Expiration Friday (32.8%)
Market adjust to the overnight time decay in the day next morning.
Conservative may create short positions in morning and close them at end of trading session. (pg44) This is best on the Friday preceding expiration week, compensation price change of 19%. However market response is not 100% efficient. The full amount of intersession loss is often not realised unless the trade is left on until the next open.

Sample Trade (page 46)
Stock $123
10 Long $120 calls 
30 Short $125 calls
If stock consistent, generate 95% profit.
If stock climb $2, still profit (52%) due to long trades. Furthermore if stock pinning effect holds and stock pins to $125, positions can be held till expiration ($125 calls expire worthless)
Downside- stock decline rapidly the next day. Unlikely, even if stock open down 10%, the long side can still retain half its values, and can close with just a small loss. Risk/Return very favourable.
The bigger risk is stocks rallied beyond the upper strike price, and way beyond the long hedge.

Conservative traders (including the author) can structure this trade on Expiration Friday after market opens, as the profit potential is enormous and risk is limited to very moderate time decay.
a) simplest is to purchase long straddles on stocks with a history of large expiration day price changes
executed at point of symmetry when stock crosses a strike price during midday flat IV window.
Open Interest and Option volume at various strikes can indicate price movement 

Chapter 2- Finding out the population statistically more probable for our day trades.The population of stock, must be heavily traded, with large open interests.

a) AAPL, APA, DNA, DVN, FDX, GOOG, GS, IBM, LMT, MA, MON, RIG, RIMM, SHLD, X
b) AAPL, GOOG, GS, MA, RIMM
These (a) stocks and (b) stocks are 73% and 125% mor e likely than expected to close expiration within $0.20 of a strike price.

Table 2.2 Summary Data for 5 stocks (12 expirations)
Comparing the number of minutes that contains a strike price cross to the number of minutes where each stock traded more than $1 from a strike (The final column lists the number of expirations within $0.30 of a strike)
________________________________________________________________________
Ticker    Minutes >$1 from strike    Strike Crosses    Ratio   Expirations <$0.30 from Strike
________________________________________________________________________
AAPL       2847                                   147                     19.37          2
GOOG     2740                                   498                     5.50            4
GS           2845                                   285                     9.98            2
MA           3100                                   306                     10.13         1
RIMM       1952                                   223                     8.75           3


AAPL is statistically 19 times more likely to trade $1 ITM than to cross a strike while GOOG is only 5.5
Hence Short Straddles on GOOG, and Long straddles on AAPL

MA has high Strike crosses (306), and only 1 expiration <$0.30 for 1 year. In percentage term, 6.6% of expiration day minutes involved a strike cross for MA. MA has more long straddles.
GOOG has high IV after earnings, good for short positions. Ratio trades as well as short straddles, with GOOG having pinning effects.

AAPL- most strike crosses occure earlier in the dayy when the stock is more active, long straddles are often a profitable trade. 38% and 76% occurred before 12:00 and 14:00.
In most cases, holding these trades beyond 14:00 will reduce or eliminate all profits.
More than 50% profit is commonly

Evening before Expiration Day
Ratio trade 1:2 or 1:3 depends. Best to take advantage of time decay that is heavily on Thurs.
Another option is long call/short call both OTM
Stock-$164, long $165/ short $170 (1:3)
Best to close on Friday evening and restructure new trades meant for Expiration Day Trading.

Earnings declaration
Long straddle and long strangle don't work due to efficiency of market and large stock movement needed.


Chapter 3- Ratio trade, long, short straddleRatio trade on Expiration Friday
1 long vs 3 short (1:3 ratios not fix, adjust based on as delta neutral as possible)
As both sides can generate significant profit, it is not meaningful to think of it either as a long position hedged against downward spikes, or short positions hedge with long options. Both are correct.

If it goes in short direction, the decline in prices due to IV collapse more than offset the increase in values of the shorts. (unless it goes down in very large amount)
If it goes in long directions, the long positions appreciate in value.
Cost of trade is minimal, as short positions pay for the long positions.

Long straddle
-most profitable when stocks in constant motion (page 134)

-after a long calm period, when stocks display high level of activities (page 134)
- move from 1 strike price to another strike price

long straddle after 1030am, when IV stabilise. (page 132)
Timing very important as initiating a long trade at the open or very late in the day can be dangerous because both are commonly characterised by rapidly falling implied volatility. In additional, when a stock trades near a strike price, the closing hour is often distorted by unusually small price changes

Short straddle
- A short position is an excellent choice whenever a stock climbs from 1 strike to another late on expiration Friday, crosses the new strike, then falls back and stabilises (page 137)

Long straddle during mid day stability window when IV was relatively steady and stock was active
short straddle late in the day after the stock had gravitated to strike price, and IV was collapsing.
Strike price effects drove the jump from from $210 to $220 (long straddle) then it sticks to $220 (short straddle)


Sunday, October 26, 2014

Book Summary of "Profiting with Iron Condor Options"

Iron Condor is the mathematically most efficient way of utilising your capital in the option markets. Most efficient does not mean it is most profitable. Most option traders make the mistakes of stuff all the capital in options as much as possible, thinking that they only make money when they are in the market.

They couldn't be more wrong.

Choose to enter the market when it is ideal, not indulge in it anytime you want.
This book taught me to look out for ways to effectively profits from Iron Condor, and to exit the market as soon as possible, and wait for another entry to set up the Iron Condor.

A great book. I would be referring to it as much as possible.


Profiting with Iron Condor Options
Author-- Michael Hanania Benklifa

Time Decay - Theta
Effect of a chance in price of underlying security - Delta
Acceleration - Gamma
Volatility - Vega

We are trading time.
ATM options decays differently than OTM

ATM decay - Waterfall, it accelerates towards the end.
OTM decay- value drops dramatically then levels off closer to expiration (because no much value to lose near the end)
Because of OTM decay, we dont hold contracts till expiration.

Dont wait till expiration. Exit as long as you have earned a decent % profit within a % length of the contract.
For example, 29% of total credit with 25% of the length of contract, 71% of total credit within 50% of length.
Out of Market means u are not exposed to market risk.
"Dont push your luck"

Volatility
IV divided by 16 times square root of number of days = how much the price will move for 1 Standard Deviation (68%)

Options are hedges, like puts bought to hedge against stocks portfolio hence buyers may overpaid for them, that is why IV higher than historical volatility (Volatility Gap)

Iron condors best on stocks with large number of strikes, reasonably high priced, high liquidity in OI & volume, price not dramatically affected by specific news.
Best- SPX, NDX, RUT, all European options (SPY is american option)

Placing a Trade
Trade works best when it is set up as a reaction to the market.
Only time when u do not react to market conditions is when u first enter the trade.
You want an iron condor that is
(1) range bound (2) long enough (3) profits

1) Time
2) Position
3) Price

"Art of the Imperfect Trade" satisfy two of the three conditions is enough.
"Keep one third as profit"

Sell when got spike in IV.
The day after expiration has many buyers jumping back, which dampens the price.
A month from expiration seems most favoured but it is too near for risk management.
A condor placed the friday before the previous month's expiration, for 5-6weeks for best. 7-8weeks is also good depending on situations.

Keep a lookout for ViX spikes and if VIX prices break upper Bollinger Band.
VIX ATM puts & calls should be same price. If not, it is a hint of things to come.
Also if next month ATM prices are substantially higher than this month, it may indicates potential large drops in future.

Delta
Delta is not symmetrical, as prices fall far faster and steeper than they climb.
Strike at Delta 10 should be much further away on the put side than the call side.

Price
Evaluate credit as a percentage of total margin at risk. for example, credit of $1,000 as % of margin received of $10,000.
Do SPX at quarter step, 1950, 1975, 2000, as liquidity is greater there, which implies tighter bid-ask spread.
Easier to balance Deltas when short strikes at these quarter strikes, as SPX has tendency to gravitate to these prices because of greater liquidity in options, futures and ETFs-: trade with the institutions, not against them.

Every $0.25 credit received for selling a SPX iron condor is abt 1% return on margin.
Therefore $1 is 4%, $2 is 8%.
Plan in advance what price you received, and what price to close it, to get your % return.

Putting it together
Position- Delta 10 positions outside previous highs & lows. Charts not trending strongly in either directions.
Price: high credit of $5 (20% of margin) volatility, which has been trending nicely, just had a 1-day spike.
Time- expiration in 4-5weeks

You can only choose 2 out of 3, prioritize.
Price is your first consideration.  You want to capture a portion of the credit, but not all. Keeping 1/3 or 1/4 is easier than waiting long enough to capture 1/2.
Then position is directed by price. If Delta 10s cannot provide the good price, you need to wait till it does (Volatility spike) or trade the farther out month. Position is NON-negotiable.
-->> Time is negotiable. Time is the only constant in trading condors. Keep a "reserve" of time in your trade so that you have time to make adjustments. It allows you when to remove or adjust your trade.

When enter a trade?
Trade out of opportunity (volatility), not out of necessity (time expiration).
Wait for a jump in VIX, it can be a percentage term relative to previous day.
Or as a break in the upper Bollinger Band on the VIX.
Or standard deviation in change in prices of VIX or S&P is greater than 2 SD

1) Get a min $3 credit or greater, which is 12% return on margin.
2) Delta shld be 10 or less, but never greater than 12.
3) Expiration day must be no closer than 49days, if volatility take a huge jump before day 42, consider it, but prefer to trade the month farther out.
4) Call short strikes shld be at least 100 to 125 points higher than current prices
Put short strikes shld be at least 125 points lower.
This cushion not just allow you to stay out of assignment, it allows you to adjust.
5) Trade when SPX is at quarter price.
6) Enter on a volatility spike day (a down day)

Sideway market - Take profit once achieve target, do not push your luck. Market do not stay sideway for too long

Uptrending mkt-
Up is good, but up too fast is not good.
Best to wait until a down move in mkt.
Reminder that volatility is up when market goes down, but not up when market goes up.
In uptrending, leave room for market to go higher. Lean on quarter prices to enter. Wait for market to finish 1 leg up to quarter price, if it can't and fall to lower quarter price, use as reference. Preference is still to enter on a down day, with spikes in volatility
IV ought to be higher than HV.

Exit is key to profit.
Exit strategy that works best is to give back almost all credit. Profits of 3% in a few days is considered good.
Don't stay through expiration as Gamma may burn u. When u exit u r now a buyer and choices may be against u.

Exit profits- good to set GTC profit exit price immediately after enter. Place order before market opens if its in your favour, to take advantage of amateur hour.
Exit time- close expiration a month before expiration, to have a wider defensive. If you staying because market moves against you, rapid time decay is your ally.
Close 2-4weeks after entering.
Exit P&L Curve- take profit without hesitation. Disappointment in less profit is better than disappointment in losses.
Exit Capital- preserve capital. If lose money, exit at break even. Lots of small gains and an occasional loss is key to success.

Can sell condors 2-3 days before holidays and long weekends.
Buy back to close right before the weekend, when Theta is discounted.
Prices decline abt midday on Friday or day prior to holiday, & drop quickly in final few minutes.

Why not close after hols? Remember events during hols can ruin your positions too. Berlin wall.


Downtrend days
Good to setup due to spike in VIX.
First & last hours are unstable and strong reversals in 1st hour are not unusual. Can just take profit and run. Or enter at this point of great uncertainty, for the VIX

Sometimes VIX continue to climb after u enter, make ur positions in losses.
U close the side that is farther, open a newer, nearer one for extra credits.
Can use credits to shift other side.
Can exit the trade too in a small loss or break even to open a new one another time.

Warning, if SPX reach 50 points near to 1 of your side, better adjust.
Another sign is when delta is more than 30.

A good trade
1) Making sure condor was large
2) trading at quarter strikes
3) selling 10 delta
4) making sure the initial credit was high
5) making proper adjustments to condor to protect principal

Adjustment rules
1) easier to adjust in a down market as you get more credits for rolling down the call credit spreads
2) harder to adjust in an up market because you do not get much for rolling up the put credit spread and you bring the position closer to your downside risk
3) trade the math, don't let delta go over 25 to 30
4) when possible, adjust when the market is moving in the opposite direction intraday. Adjust the puts when the market rallies, or adjust the calls when the market dips.
5) trade only what is in front of you, and not what you or anybody else thinks that the market will do.
6) if you must speculate, assume worst-case, not the best-case scenario
7) if you must adjust, consider getting out at breakeven at the first chance available
8) you can always put in a new trade with better strikes

Manage your risk, take the loss, reduce your exposure when necessary.
Wing buyback only if you have a strong conviction that the market will reverse direction

Day Trade before Earnings Day
IV 1st month / IV 2nd month
IV May / IV June (for example)
If this Sort Value is more than 1, then there is a skew worth speculating.

Use the same principles to open iron condors, on the options that are going to expire soon.
Seek Deltas below 10, but you can afford to be more aggressive with the call sides.
Look to close the positions right at the 1st hour, take profits.

Look at the ATM calls, what is the price, add to the current price of stock, to know that is the expected price speculators expect the stock to rise to.
Same for ATM puts, but minus instead.

Trade with delta 10, get credits, quit on the day earnings or the NEWS are announced, immediately asap.
You may lose some trades, win most.
Most trades will win due to the shrinking of the volatility. However, keep your trade small as inevitable, some iron condor will fail.


Thursday, October 23, 2014

Book Summary of "Get Rich With Options" By Lee Lowell

This is the first book I read that let me understand more about options.

It is not technical, and not dry, allows me to get interested in options, before I took on more technical books that explains more on options, the greeks involved.
I have read a lot of books, and summarised them in my notepad.. will slowly blog them out to share with anyone who are interested in option trading as an income generating strategy.

Hope this Summary helps anyone who is interested!


Get Rich with Options - Lee Lowell


Calls - the right to buy at a strike price, before expiry date
Puts - the right to sell at a strike price, before expiry date

Option calculator of delta, option pricing

Delta- 
the percentage relationship of security price with your option price
Example 0.60- When the underlying security moves up $1, your option price moves up 0.60

Volatility
HV - Historical Volatility (based on historical) and IV Implied Volatility (forward looking)
The higher the volatility, the higher option price is
The lower the volatiltiy, the lower option price is
Buy and sell at opportunate time
option price of different stocks may varies a lot due to volatility.

Reverse Skew (usually stocks)
For certain stocks, as strike prices goes down, the implied volatility goes up, due to fear factor of downside moves, this is known as reverse skew. People start paying higher price for downside protection, which inflates option prices, which in turn heats up IV numbers.

Forward skew
As strike prices goes up, IV goes up. Typical for soybean market, especially during summer growing months.
Soybeans trae wtih IV levels getting higher as you move up in strike prices. As dry summers can produce potential droughts and a reduced supply of soybeans, investors tend to favour buying upside protection, which causes more interest in upside strikes.

Smiling Skew
Incorporates a reverse skew and a forward skew
A forward skew develops when the higher-strike options have an increasing large IV. ATM is usually at bottom of the IV curve

Spread - buying 1 option and selling 1 to hedge
1) hedging keep initial cost down and allow more trades
2) spreads can offset an option purchase a lower IV with a sale of option at higher IV. - getting the "volatility edge"

Strategy 1- Buying DITM options on stocks / indexes

Idea- to spend only 50% or less of the stock costs, to control the same amount of stock, using options, and enjoy close to the same price movement (hence to seek delta > 0.9), and with limited losses.
To close this position once profitable, to not hold till the expiry.

1) Choose the deepest DITM option, that has a delta of at least 0.9 and above
2) Choose the lowest strike price possible.
3) If you have choices, try to choose the one with the nearest breakeven price (strike price + premium)

End-results
1) Expire worthless
2) Sell options at any time
3) Roll your options (sell and then buy a new DITM option
4) Exercise the call options and own the assets

Benefits-
1) Lower up-front cost
2) Less Capital at risk
3) Maximum movement- high delta
4) Higher ROI
5) With less capital and lower cost, you can divert funds to other low risks assets

Drawbacks
1) No dividends nor voting rights
2) Expiry dates

Strategy 2- Get paid to buy stocks "naked put selling"
Idea- To own a stock at a lower price than current market price, but instead of waiting for prices to drop and buy, sell naked put options for an income. If prices drop below your targeted price, you would be forced to execute but that is alright as you want to own the stock anyway.
Do not sell naked put options on stocks that you don't want to potentially own.
Good to go in when valued stocks get hammered down, the IV will make put options even more expensive.

1) Choose a stock that you like to own, potentially for long term.
2) Choose a lower price than its current price, that you would think is a bargain
3) Sell a put option
4) Collect income most of the time, and be prepared to execute it if needed

Margin requirements = [(20% of underlying price) + (credit received) - (amt strike price is OTM)] x 100

End-results
1) Expire worthless
2) Own stocks that you want to own, but carries risks that stocks plunge, which would affect you anyway if you outright own the stock

Strategy 3- (Most Favourite of Lowell) Credit Spread (also taught in Daniel Loh)
Sell 1 option and buy the less expensive options for credit
Bull Put Spread
Bear Call Spread

Idea- instead of choosing the price direction where you predict it will go, choose the direction you predict it will not go. This will give you extra allowance. As long as as price does not go too wrong, you benefit due to Time Decay.

1) Sell and buy nearest pair of OTM put options when you think the security is bullish.
2) Sell and buy nearest pair of OTM call options when you think the security is bearish.
3) Sell the more expensive, and buy the cheaper options, for positive credits into your account. (hence credit spread)
4) Debit spread is when you sell the cheaper option, do it only when you are very confident of the directional bias, meant for punting, not a credit spread earning.
5) Wait for time decay or close for profits

Best trades- majority of your trades.
Daniel Loh focusing on this strategy

Strategy #4- Selling covered calls

Idea- If you own a stock, sell covered calls on your own stocks at a higher price

1) Option premiums allow you to earn some income. higher probability
2) If you had to exercise the options, take it as an opportunity to realise your gains.
3) Same golden rule, whenever an option moves swiftly in your favour, usually good idea to buy back the position and take profits.

Strategy Bonus- Ratio Option Spreads- More risky, more rewards, need more experience

Idea- buy 1 expensive OTM options and selling multiple less expensive OTM options to hedge
Allows you to take advantage of a directional bias without incurring an initial debit or having to speculate on low probability OTM option.
Even if all expires, you keep money. As it involves selling naked options, there is a low chance but high risks of losing a lot.

1) buying an OTM option, and selling multiple, less-expensive, farther OTM options against it in 1 single spread trade
2) the multiple sales would provide extra credit on your 1 expensive option purchase
3) You will get credits if all options expire worthless
4) Best case scenario- Price moves towards the middle of the range you bought, giving your bought options profits, and making your sold options worthless
5) Selling put ratio spread is better than call ratio spread, as security can only go to zero, but can rise to infinity. However, some call ratio spreads are worth it

Smiling Skew - optimal as higher IV as you move away from ATM makes option pricing more expensive and worthwhile to sell.

Example-  Call ratio spread on soyabeans
Soyabean options great to trade at summer months, just in spring- Soybean forward skew
Nov price 604 3/4 
Buy 680 calls for 90cents
Sell 5 Nov 820 calls for 21 cents each
Total credit $1.40

if soyabeans move up to 680 - 820, you gain in bought calls of 680, but your sold options of 820 can expire worthless. Good returns
Be mindful of StopLoss, as what you do not like may still happen. SL and stay Sharp

Stock / Indexes Call Ratio Spreads
Indexes are reverse skew- sales of far OTM put options offset by purchase of not-so-far OTM put options -> big winner.

Example:- Put ratio spread on 2006 DJ 11,000
Sell 56 7000 put options for $560, and buy 3 10,400 put options for $30
If all expire worthless, earn $530 credit
If it moves to between range of 7000 and 10,400, then you earn big profits.
if it moves below 7000, huge losses.

Unlimited Risk exposure, stay sharp with SL

Related Posts Plugin for WordPress, Blogger...